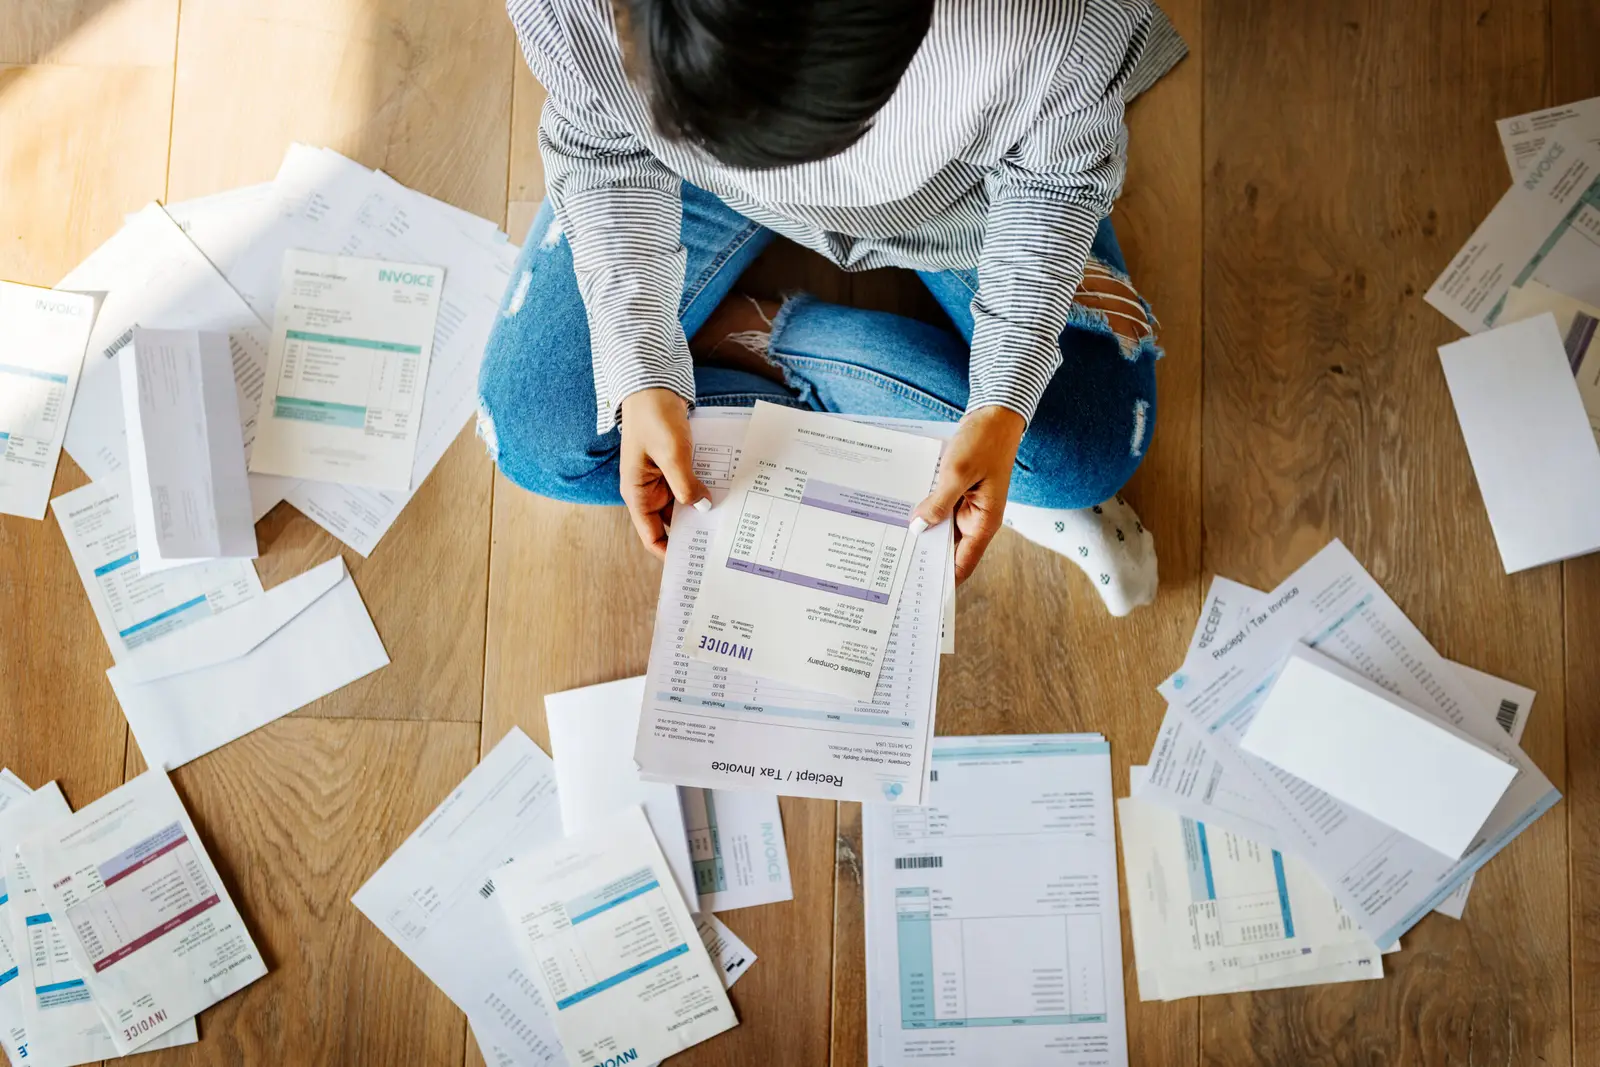
Your debt-to-income ratio (DTI) compares your total monthly debt payments to your gross monthly income, and lenders use it to gauge how comfortably you can take on a mortgage. It is one of the most important, and most misunderstood, numbers in the process.
Below 36% opens the widest range of loan options.
Add up your monthly debt obligations (credit cards, car loans, student loans and the proposed new mortgage payment) and divide by your gross monthly income. If your monthly debts total $2,400 and you earn $7,000 a month, your DTI is roughly 34%.
You have two main levers, increasing income or decreasing debt:
DTI is not a number you fix at the closing table. It is one you shape in the months before applying.
Small moves made early can meaningfully expand the loan amount you qualify for, so run the math well before you start making offers.
Second home financing requires bigger down payments, stronger credit, and more reserves. Here's what to expect, and how to fund it strategically.
Fed rate decisions don't move mortgage rates directly. Learn what really drives mortgage pricing, and how to watch the right signals.
American homeowners hold record levels of equity. See what's driving the trend, and how to put your equity position to work strategically.
A loan officer can calculate your ratio with the new payment included and show which debts are worth paying down first. Pre-qualifying will not affect your credit score.
Pre-qualify