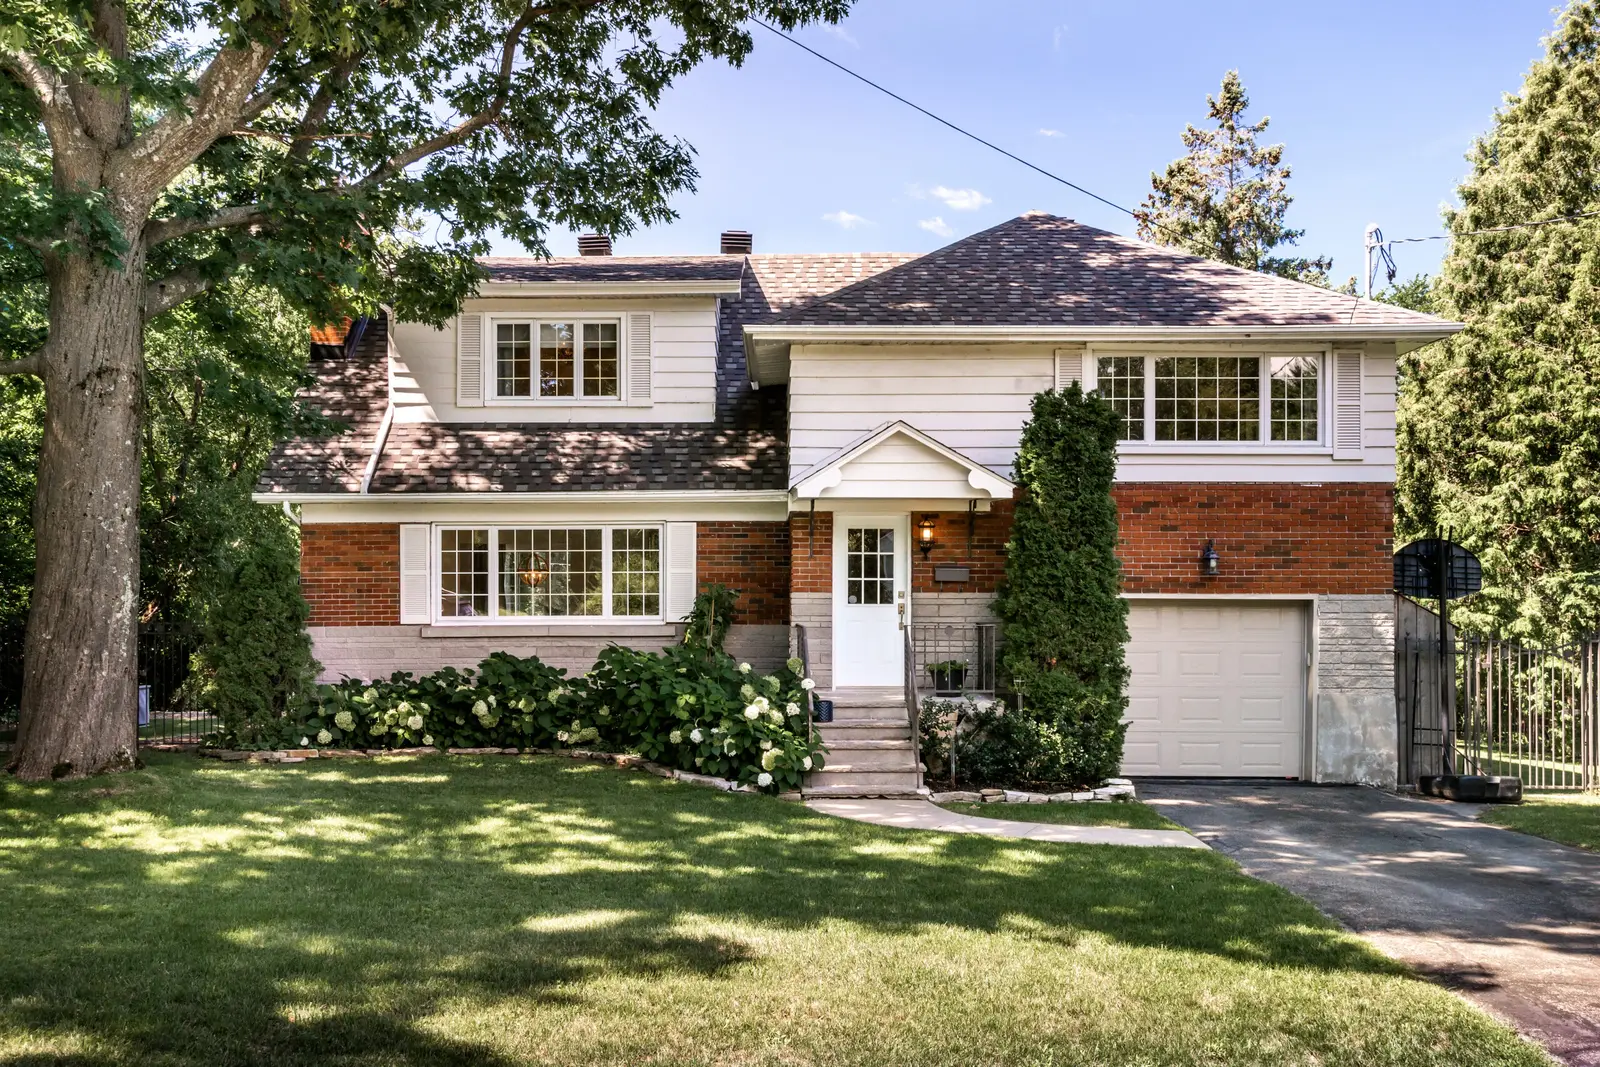
A second home, whether it is a weekend retreat, a future retirement spot or a place near family, is one of the more rewarding purchases a homeowner can make. It is also financed differently than your primary residence. Lenders see it as higher risk, and the requirements reflect that.
Rates also run slightly higher than on a primary residence.
Lenders also verify that the property qualifies as a true second home rather than an investment property. The home generally must be occupied by you for part of the year, suitable for year-round use and not rented out full-time. Misclassifying an investment property as a second home, even unintentionally, can trigger serious loan issues later.
If you have meaningful equity in your primary home, a cash-out refinance or HELOC can fund the down payment on a second property without disrupting your existing mortgage. For many buyers, that is the cleanest path to a second home without depleting savings.
Plan the financing before you fall in love with the property.
A pre-approval built for a second home purchase keeps your offer strong and your timeline realistic.
Fed rate decisions don't move mortgage rates directly. Learn what really drives mortgage pricing, and how to watch the right signals.
Your DTI ratio can make or break your mortgage approval. See the thresholds lenders use, and how to improve yours before you apply.
American homeowners hold record levels of equity. See what's driving the trend, and how to put your equity position to work strategically.
A loan officer can build a pre-approval for a second home and show whether the equity in your current one could fund the down payment. Pre-qualifying will not affect your credit score.
Pre-qualify