A kitchen remodel, an addition or a full renovation rarely gets paid for in cash. The three most common paths, a cash-out refinance, a HELOC and a personal loan, each fit a different kind of project, timeline and budget, and picking the wrong one can cost more than the renovation itself.
A renovation that raises your home's value can tilt the choice toward the equity options.
Beyond rate and speed, consider how the project affects your home's value. A renovation that meaningfully boosts equity can make a cash-out refinance or HELOC a stronger choice, since you're borrowing against value the project itself helps create.
There's no single right answer here.
Matching the financing structure to the size, timeline and certainty of your project is what keeps a renovation from becoming a financial strain.
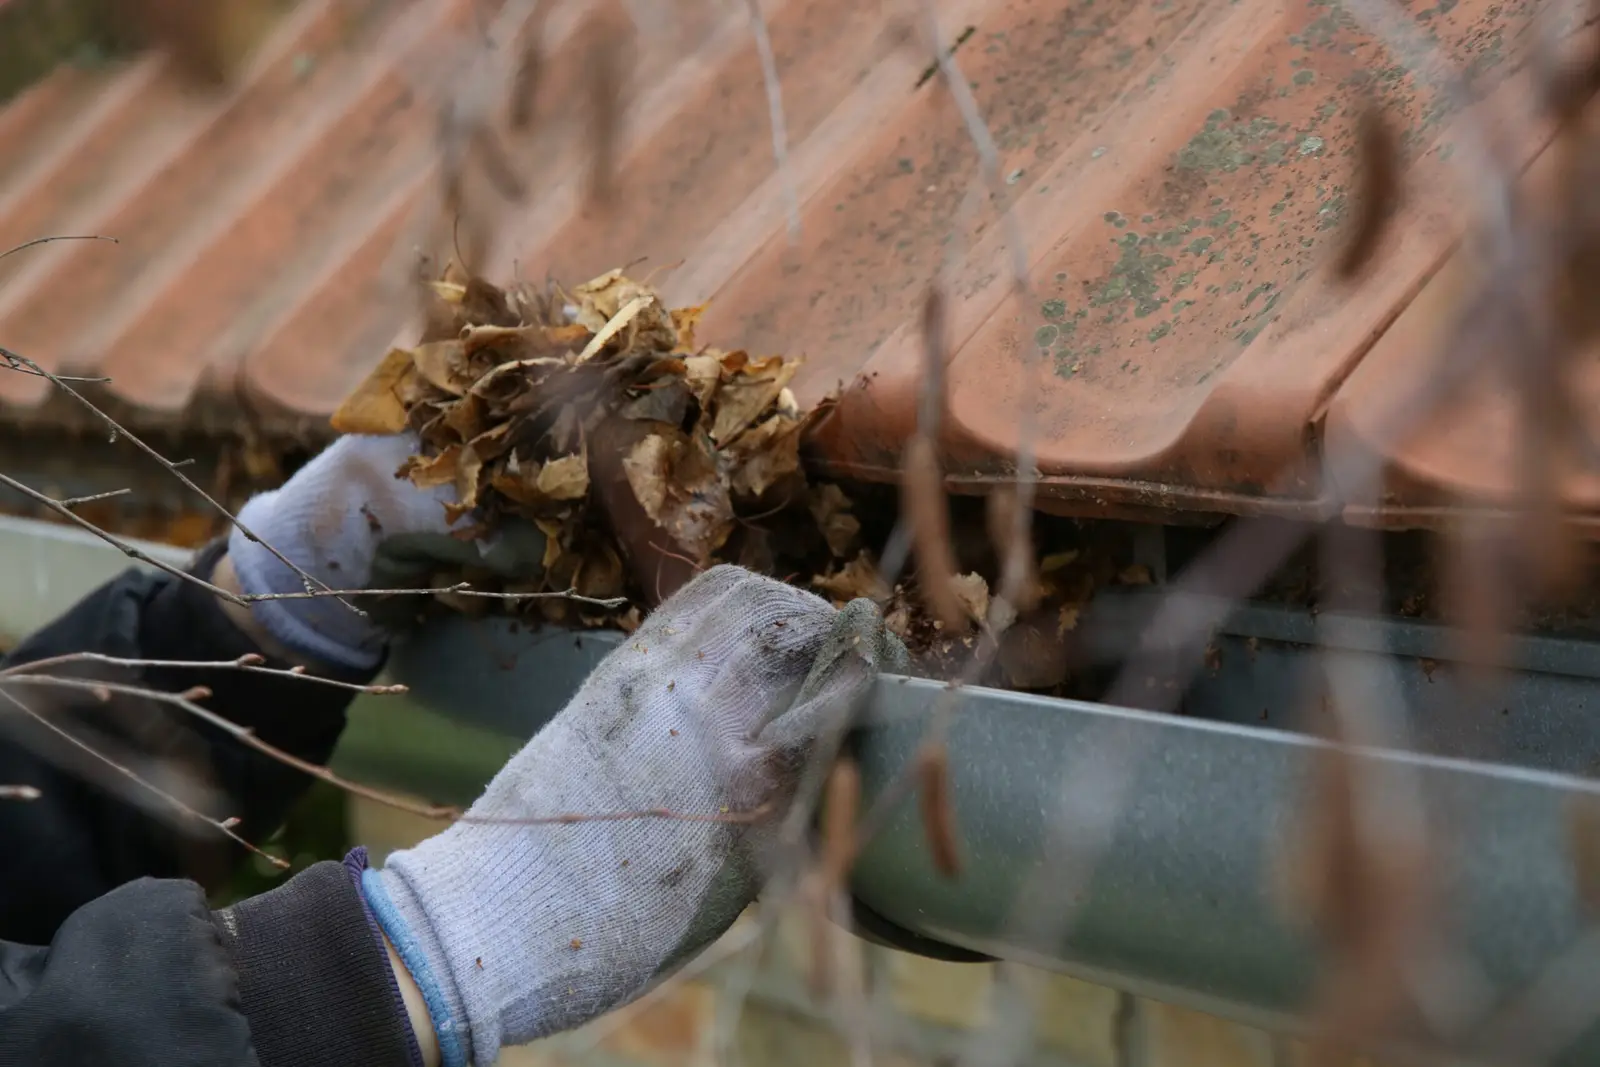
Most of what actually lowers a home's appraised value isn't cosmetic, it's deferred maintenance that turned into water damage.
Not every renovation pays you back. See which home improvement projects deliver the highest ROI at resale, and which ones rarely recover their cost.
Every November, the Federal Housing Finance Agency announces the conforming loan limit for the year ahead. Here is what the number means for your options.
A loan officer can price a cash-out refinance and a HELOC against your project budget so you can compare them before anything is offered. Pre-qualifying will not affect your credit score.
Pre-qualify