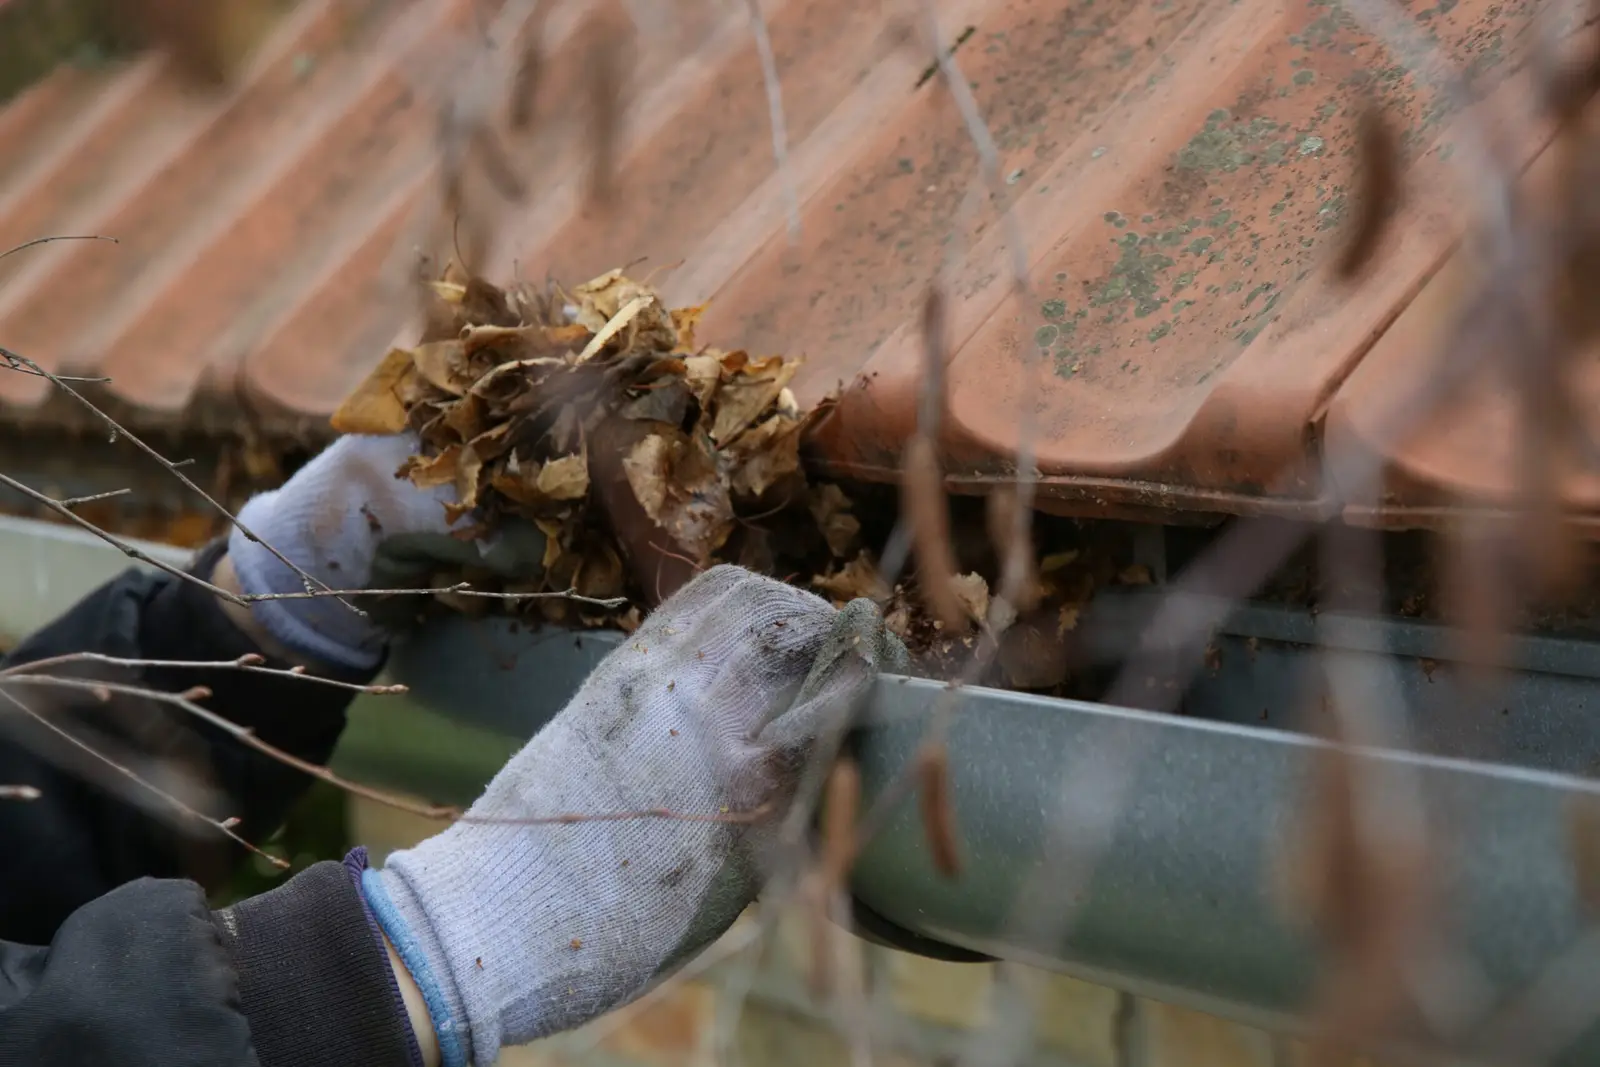
Most of what lowers a home's appraised value isn't cosmetic. It's deferred maintenance that turned into water damage, and fall is when the conditions for it set up, so a few hours of work before the first freeze prevents the repairs that later show up as appraisal adjustments or an insurance non-renewal.
A few hours of work before the first freeze covers all three.
Water management matters most.
Insurers and appraisers tend to notice the same three things: roof condition, evidence of past water intrusion and the age of major systems. Each of them traces back to the list above.
Fall maintenance is inexpensive. The foundation repair, mold remediation or coverage non-renewal that follows skipping it is not.
A home kept in good shape holds its value at appraisal, which matters whenever you sell, refinance or borrow against your equity.
Renovation financing options each fit different projects and budgets. Compare cash-out refinancing, HELOCs, and personal loans before you start.
Not every renovation pays you back. See which home improvement projects deliver the highest ROI at resale, and which ones rarely recover their cost.
Every November, the Federal Housing Finance Agency announces the conforming loan limit for the year ahead. Here is what the number means for your options.
A loan officer can show you what your home's value means for a refinance or a line of credit before anything is offered. Pre-qualifying will not affect your credit score.
Pre-qualify