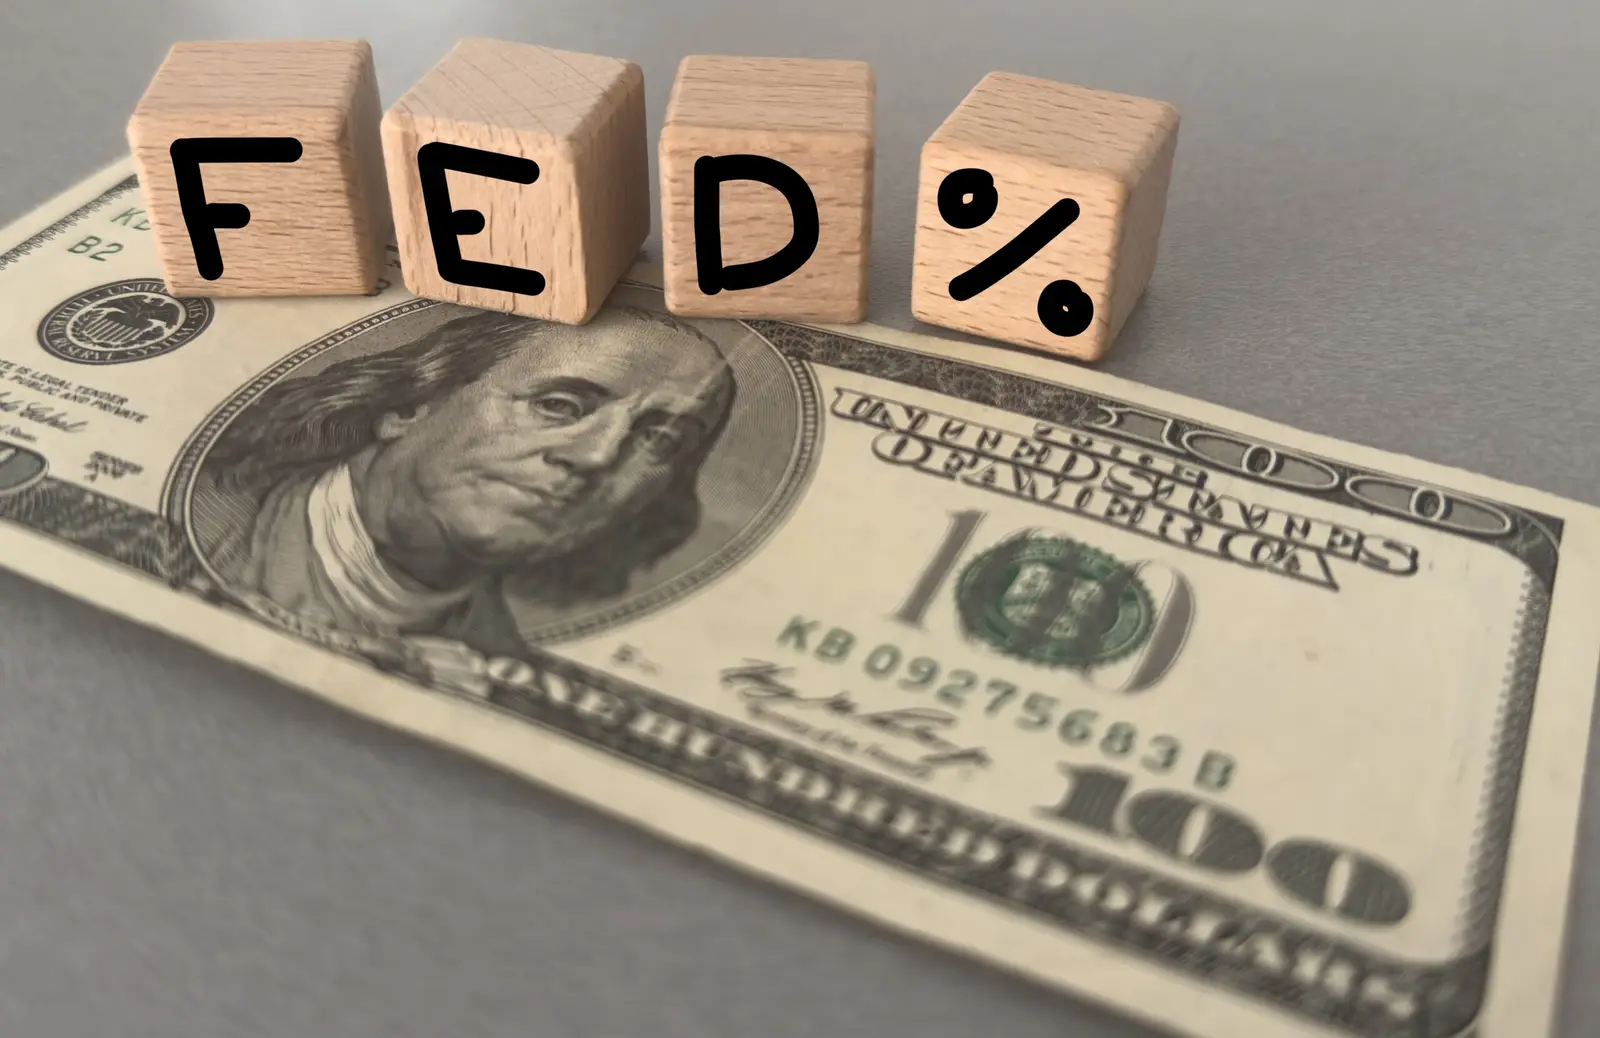
Mortgage rates rarely move in lockstep with the Federal Reserve. They track a different benchmark, the 10-year U.S. Treasury yield, which reflects investor expectations for growth and inflation over the life of a 30-year loan.
Markets often price in a Fed decision weeks before the meeting.
Every time the Fed meets, headlines suggest mortgage rates will follow whatever it decides. They usually don't. The federal funds rate is a short-term bank lending rate that directly shapes credit cards, HELOCs and auto loans.
Watching the Fed calendar is a reasonable habit, but it's an incomplete signal.
Borrowers who follow Treasury yields and inflation trends alongside Fed meetings get a far clearer read on where mortgage rates are headed, and can time a rate lock with more confidence than the headlines alone provide.
Mortgage-backed securities quietly shape the rate you're offered. Here's a plain-language look at what they are and how they influence pricing.
Self-employed borrowers face a different mortgage path. Learn what lenders look for, what documents you need, and how to strengthen your application.
Jumbo loans don't always cost more than conforming loans anymore. Here's how jumbo pricing and qualification work in 2026.
A loan officer can walk you through where Treasury yields and inflation data stand before you decide when to lock. Pre-qualifying will not affect your credit score.
Pre-qualify