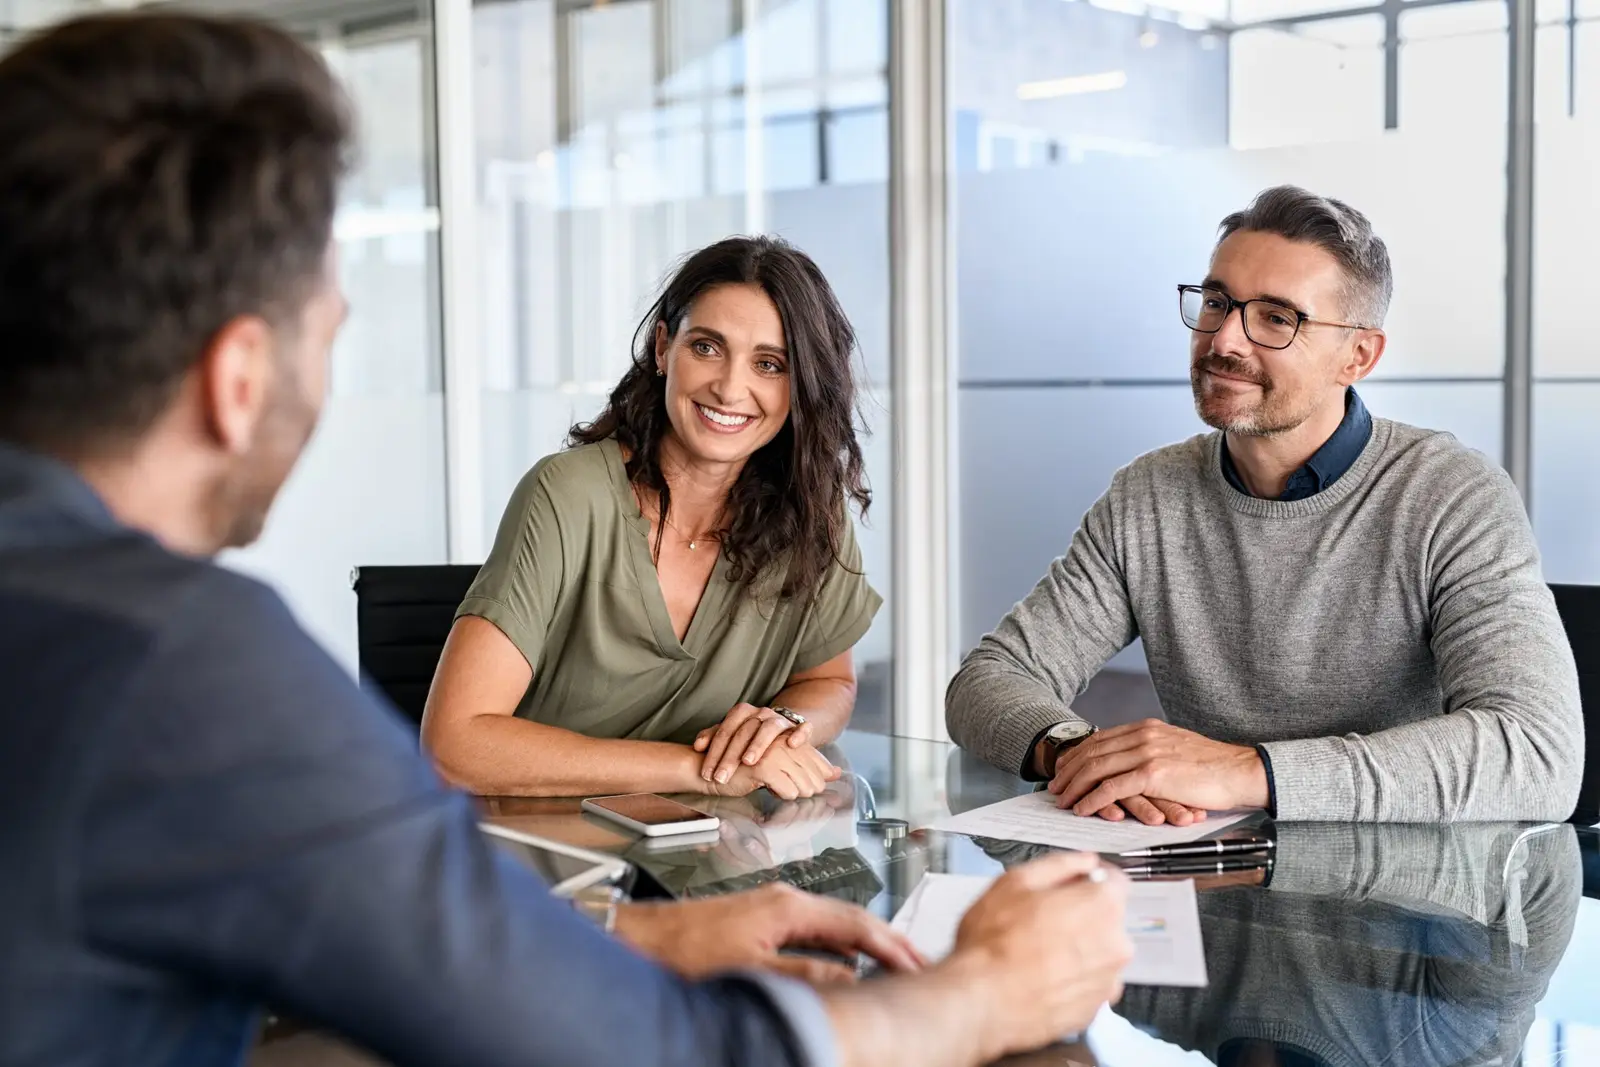
For freelancers, business owners and independent contractors, getting a mortgage isn't harder so much as it's different. Lenders ask for extra documentation on self-employment income, but qualified applicants get the same loan programs and competitive rates as W-2 employees.
Lenders typically average your last two years of income.
The most common challenge for self-employed borrowers is showing consistent income. Lenders typically average your last two years, and big swings, or a year of lower income, can reduce what they'll use to qualify you.
The mortgage market has more flexibility for self-employed buyers than it did a decade ago.
For non-traditional or fluctuating income, bank statement loans and other non-QM products may also be options. The key is preparing your documentation early and working with a lender experienced in self-employed underwriting.
Locking your mortgage rate protects you from rate increases, but timing matters. Learn when to lock, when to float, and what each strategy costs.
The same borrower can get very different mortgage quotes. Learn why rates vary between lenders, and how to shop smart for a better deal.
Inflation is one of the biggest drivers of mortgage rates. Learn how the connection works, and what it means for buyers and homeowners today.
A loan officer can review your returns and statements up front, show you which income a lender is likely to use, and point you to programs that fit how you earn. Pre-qualifying will not affect your credit score.
Pre-qualify