A pre-qualification and a pre-approval sound interchangeable, but they carry different weight with sellers and with your own planning.
Pre-approvals typically last 60 to 90 days and can be refreshed. Neither is a final loan commitment.
A pre-qualification is a quick, informal estimate based on information you provide, usually without document verification. It is useful for early budgeting and a rough price range, but it does not represent a lender commitment.
A pre-approval is significantly stronger. The lender pulls your credit, reviews your income and assets, and issues a letter stating how much you can borrow and under what conditions. In competitive markets, a pre-approval letter is often the minimum a seller expects before considering an offer.
Getting pre-approved early does more than strengthen your offer.
It also tells you, honestly, what you can afford before you fall in love with a home outside your range. You can pre-qualify first to get a feel for your price range.
Your mortgage is only part of the cost. Learn the taxes, insurance, maintenance, and fees most first-time buyers underestimate, and how to plan ahead.
Over 2,000 down payment assistance programs exist nationwide. Learn the four types of help available and where to find programs in your area.
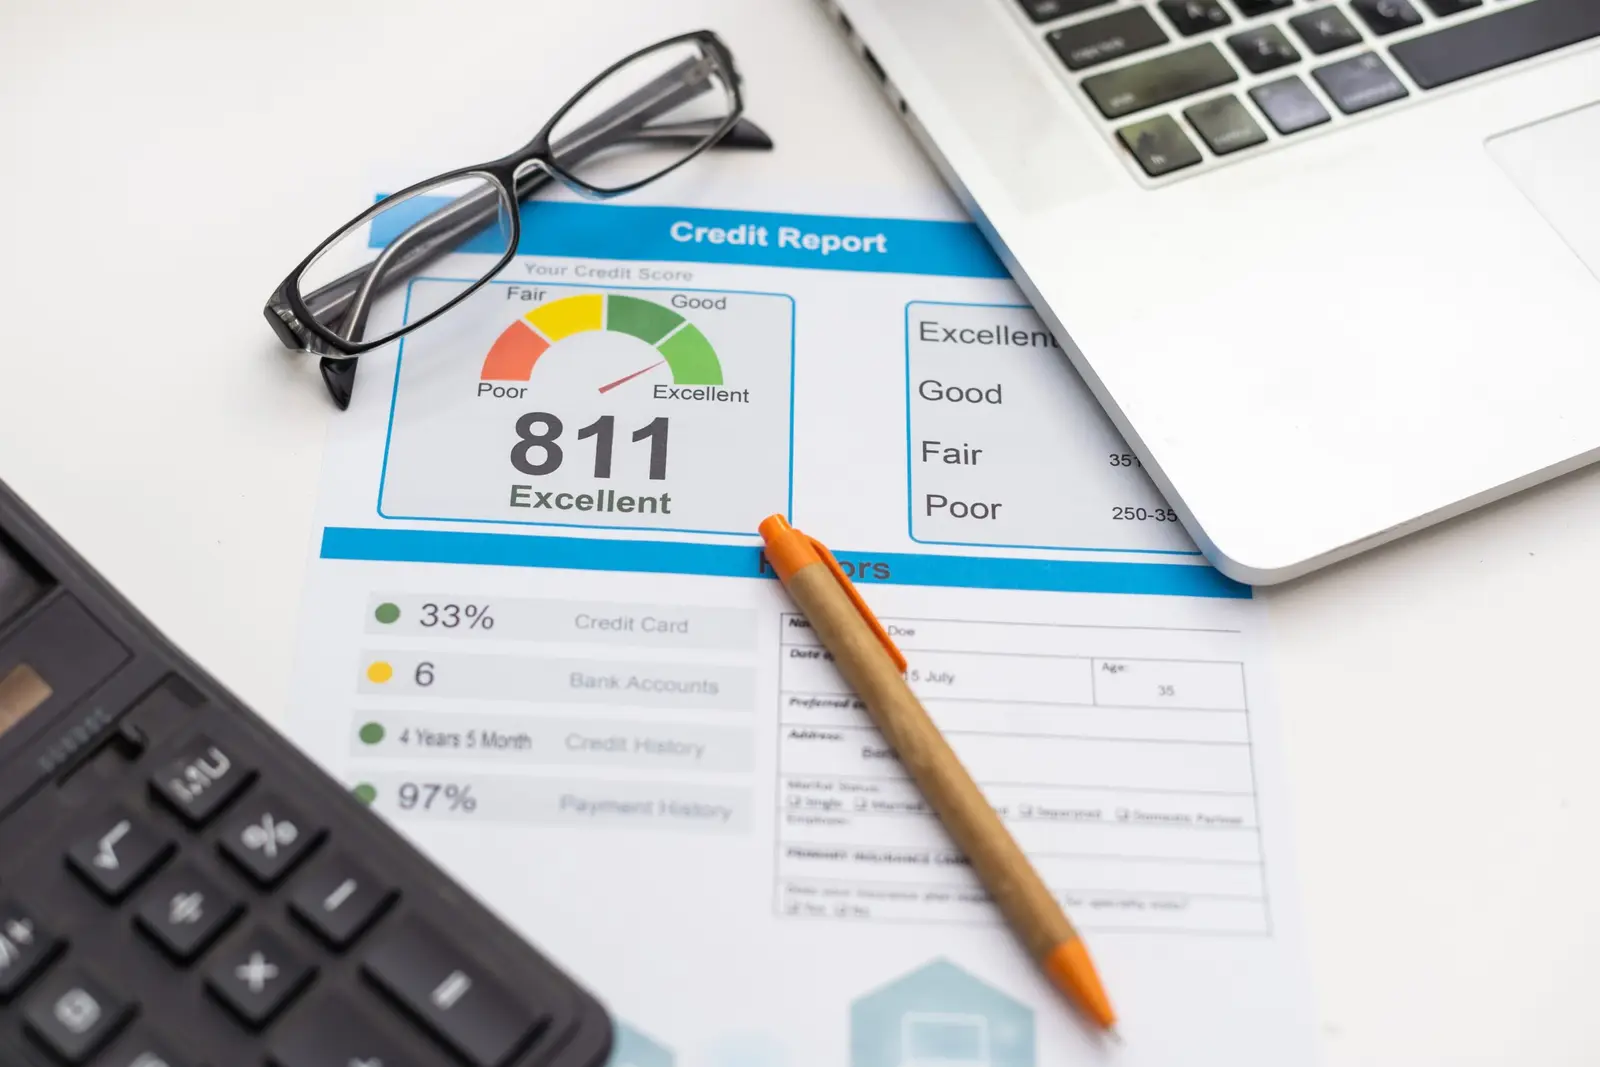
A higher credit score can save you tens of thousands over 30 years. See the score tiers that matter, and proven ways to boost yours before applying.
A loan officer can move you from a rough estimate to a pre-approval letter that sellers take seriously. Pre-qualifying will not affect your credit score.
Pre-qualify